Can't Pay EMI After Job Loss? 7 Steps to Protect Yourself from Debt and Harassment

Updated: 4 days ago
Losing a job can turn a normal EMI into a heavy burden overnight. If you can't pay EMI this month, do not panic and do not hide from the problem. A missed payment can lead to late fees, lender calls, CIBIL impact, and recovery pressure, but there are still practical steps you can take.
This guide explains missed EMI what happens, what lenders usually do after 30, 60, and 90 days, and how to protect yourself from debt stress and recovery agent harassment. It is written for Indian borrowers dealing with job loss, salary delay, or sudden income drop.
This article is for general information only. It is not legal, financial, or mental health advice. For personal guidance, speak to a qualified professional.
What happens when you can't pay EMI after a job loss
Missing one EMI does not mean everything is over. But it does start a chain of events. The faster you respond, the more options you usually have.
Late fees and penalty charges
Most lenders charge a late payment fee when an EMI is missed. They may also add penal interest on the overdue amount. These charges can make the loan harder to catch up on if you ignore it for several weeks.
Check your loan agreement or lender app for the exact charges. If you cannot find them, ask the lender in writing.
Calls, messages, and payment reminders
After a missed EMI, lenders and collection teams may call, message, or email you. Early calls are often reminders. If the overdue amount grows, the tone may become firmer.
You do not have to avoid every call. A short, calm response is better than silence. Say that you have lost your job, you are reviewing your finances, and you will send a written request for relief.
CIBIL and credit score impact
When EMIs remain unpaid, lenders may report the delay to credit bureaus such as CIBIL. This can affect your credit score and make future loans harder or more expensive.
A single late payment may not have the same impact as repeated delays, but it should still be taken seriously. Your goal is to communicate early and keep a written record of what you asked for.
SMA and NPA stages explained simply
Banks and financial institutions classify overdue accounts in stages. The exact handling may vary by lender and loan type, but the broad idea is simple.
Stage | Simple meaning | What it means for you |
SMA-0 | Overdue up to 30 days | The lender sees early stress. You may receive reminders and late fees. |
SMA-1 | Overdue for more than 30 days and up to 60 days | The account looks more risky. Calls and follow-ups may increase. |
SMA-2 | Overdue for more than 60 days and up to 90 days | The lender may push harder for payment or restructuring. |
NPA | Overdue for more than 90 days | The account may be treated as a non-performing asset, and recovery action can become more serious. |
SMA means Special Mention Account. NPA means Non-Performing Asset. In plain language, the longer the EMI remains unpaid, the fewer easy options you may have. That is why early action matters.
7 steps to protect yourself when you can't pay EMI
These steps are not about running away from debt. They are about staying organised, reducing damage, and choosing a realistic path.
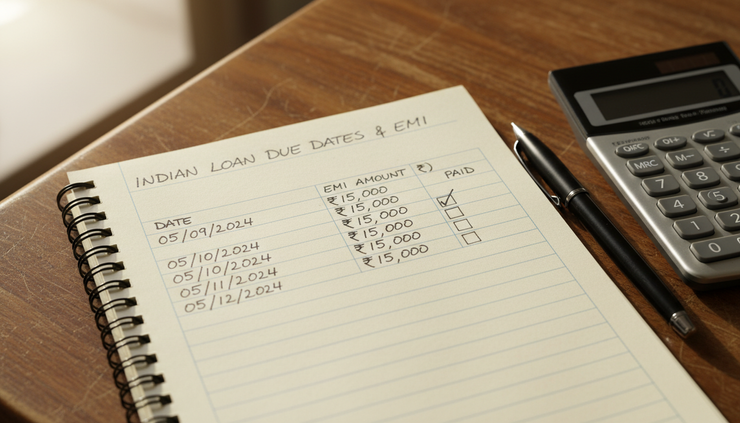
1. List every loan and its due date
Start with a full list. Do not rely on memory. Write down each loan, card, app loan, personal loan, vehicle loan, home loan, gold loan, and money borrowed from friends or family.
Include these details:
Lender name
Loan type
EMI amount
Due date
Outstanding balance
Interest rate, if known
Late fee or penalty, if known
Security or collateral, if any
Current status, paid, overdue, or likely to bounce
This list will show which payments are urgent and which lenders need immediate communication.
If several EMIs are due in the same week, mark them clearly. A bounced auto-debit can also lead to bank charges, so check your account before the due date.
2. Prioritise secured and essential debts
When money is short, every lender may sound urgent. But not all debts carry the same risk.
Give higher priority to:
Home loan or loan against property
Vehicle loan, if the vehicle is needed for work or family needs
Gold loan, if important family assets are pledged
Rent, electricity, food, medicines, and school fees
Any debt where missing payment can quickly affect shelter, transport, or basic living
Credit card dues and personal loans are serious too, but secured loans can carry direct risk to an asset. The aim is not to ignore unsecured loans. The aim is to avoid losing essentials while you work out a plan.
3. Inform lenders early in writing
If you know you may miss an EMI, write to the lender before or soon after the due date. Do this even if you have already spoken on the phone.
A written message creates a record. It also shows that you are not ignoring the loan.
Your message can be simple:
I have lost my job and my income has stopped temporarily. I am unable to pay the full EMI on the due date. I request short-term relief, restructuring, or a revised repayment plan. Please confirm the options available to me in writing.
Send it by email, lender app, or any official support channel. Keep screenshots and acknowledgement numbers.
Avoid making promises you cannot keep. Do not say, “I will pay everything next week,” if you are unsure. A realistic update is better.
4. Ask for an EMI holiday, restructuring, or tenure extension
Many borrowers hear the word “default” and feel there is no way back. That is not always true. Ask your lender about hardship options.
Common options may include:
Temporary EMI relief or moratorium
Part payment for a short period
Loan restructuring
Tenure extension to reduce EMI size
Conversion of overdue amount into a revised plan
Reduced interest or fee waiver, if the lender agrees
Loan restructuring means the lender changes the repayment terms. This may reduce short-term pressure, but it can also increase total interest or affect your credit record. Ask for the full terms in writing before agreeing.
Questions to ask the lender:
What will my new EMI be?
Will my credit report show restructuring?
Will the total interest increase?
Are there processing fees?
What happens if I miss the revised EMI?
Can recovery calls pause while the request is reviewed?
Read the revised terms slowly. If needed, ask someone you trust to review them with you.
5. Do not borrow from new loan apps to pay old EMIs
When recovery calls start, a quick loan app may feel like a rescue. In many cases, it creates a deeper trap.
Avoid taking fresh high-cost debt only to pay an old EMI, especially if you do not have new income yet. It can lead to:
More EMIs due next month
Higher interest and charges
Multiple recovery teams calling at once
More stress and confusion
A larger settlement problem later
If you are considering a new loan, ask one hard question.
Will this loan solve the income problem, or only delay it for a few weeks?
If there is no clear repayment source, pause. Speak to family, a trusted adviser, or a debt relief professional before taking another loan.
6. Know your rights with recovery agents
Recovery follow-up is allowed, but harassment is not. Borrowers have the right to be treated with dignity.
As a general rule, recovery agents should contact borrowers at reasonable hours, usually between 8 am and 7 pm. They should not use threats, abusive language, public shaming, or repeated calls meant to intimidate. They should not contact neighbours, colleagues, or relatives in a way that violates privacy.
If you face recovery agent harassment, take these steps:
Stay calm and avoid arguments.
Ask for the caller’s name, agency name, lender name, and authorisation details.
Tell them you want all communication in writing.
Save call logs, messages, and recordings where legally allowed.
Do not allow anyone to enter your home without proper authorisation and your consent.
Report abusive behaviour to the lender’s grievance team.
Escalate to the lender’s nodal officer if the issue continues.
If you feel unsafe, seek help from local authorities. Debt does not remove your right to safety and respect.
7. Consider settlement if recovery is not realistic
Sometimes job loss lasts longer than expected. If your income has fallen badly and regular EMIs are no longer realistic, loan settlement may be an option.
Settlement means the lender agrees to accept a lower amount as a final payment, subject to written terms. It is usually considered when the borrower cannot repay in full and the account is already stressed.
Settlement can affect your credit report. It may appear as “settled” instead of “closed,” which can make future borrowing harder. Still, for some people, it may be a practical way to stop the debt from growing and end constant recovery pressure.
Before agreeing to any settlement:
Get the offer in writing.
Check the exact final amount.
Confirm the payment deadline.
Ask for a no-dues or closure letter after payment.
Do not pay cash to an agent without official receipt.
Make payment only through approved lender channels.
A settlement should be planned carefully. A rushed payment without written proof can create fresh disputes later.
Use this emergency budget template for the next 30 days
When income stops, your budget must become very simple. Focus on survival, safety, and essential obligations.
Use this template for the next month:
Income expected Salary arrears, final settlement, freelance income, family support, rental income, or any other confirmed money.
Cash in hand Bank balance, cash, wallet balance, and any safe emergency savings.
Must-pay living costs Rent, groceries, milk, cooking gas, electricity, water, phone, basic internet, medicines, school essentials, and travel for job search.
Secured debt payments Home loan, vehicle loan, gold loan, or any loan linked to an important asset.
Minimum debt payments possible Amount you can pay without risking food, rent, medicine, or transport.
Payments to pause or reduce Subscriptions, eating out, shopping, non-urgent travel, entertainment, and lifestyle spending.
People to inform Lenders, landlord if needed, family members, and anyone who depends on your income.
Documents to collect Termination letter, salary slips, bank statements, loan statements, CIBIL report, lender emails, and recovery messages.
This budget is not meant to be perfect. It is meant to give you control when everything feels unclear.
Debt stress is common, and you should not face it alone
Debt after job loss can affect sleep, appetite, mood, and family life. Many people feel shame, fear, or anger. These feelings are common, but silence makes them heavier.
Talk to someone you trust. It may be a spouse, parent, sibling, close friend, counsellor, or support group. Share the facts, not just the fear. Tell them what you owe, what income has stopped, and what help you need.
If debt stress is leading to thoughts of self-harm, reach out for urgent support from a mental health professional, a crisis helpline, or emergency services near you. Your life is more important than any loan.
Also, do not make major financial decisions when you are exhausted or frightened. Sleep, eat something, write down the numbers, and then decide.
How Payday Rescue helps with debt relief after job loss
Payday Rescue is a Bangalore-based debt relief and loan settlement service that helps borrowers create a practical plan when EMIs have become unmanageable.
The process usually starts with understanding your full debt picture. This includes your loans, current income, overdue status, recovery pressure, and the documents available. Based on that, Payday Rescue helps you explore possible routes such as lender communication, repayment planning, restructuring requests, or settlement discussions.
Payday Rescue may also negotiate with lenders or collection teams on your behalf, based on your situation and the documents you provide. The aim is to reduce confusion, stop panic-driven decisions, and work towards a realistic outcome.
There are no guaranteed results, because every lender, loan, and borrower profile is different. But having a structured plan can make the next step clearer.
For a free consultation, WhatsApp Payday Rescue at +91 98865 50910.
What to remember if you can't pay EMI right now
If you can't pay EMI after a layoff or income loss, act early. List every loan, protect essentials, write to lenders, ask for relief, avoid new high-cost borrowing, know your rights with recovery agents, and consider settlement only after understanding the impact.
Missed EMIs, layoffs, loan settlement decisions, and collection pressure can feel overwhelming. You do not have to solve everything in one day. Start with your loan list, send one written message to your lender, and ask for support before the situation grows harder.
Need help with payday or loan app debt?
Payday Rescue helps borrowers across India settle payday loans and loan app debt, deal with recovery harassment and plan a realistic way out. Your first consultation is free and confidential.
Related guides
FAQs
What happens if I miss one EMI?
You may face late fees, reminder calls, and possible credit reporting depending on the lender’s process. One missed EMI should still be handled quickly. Inform the lender in writing and ask for available relief options.
Will missing EMIs affect my CIBIL score?
Yes, delayed or missed payments can affect your CIBIL score when reported by the lender. Longer delays and repeated missed payments usually create more serious credit impact.
Can I ask my bank for loan restructuring after job loss?
Yes, you can ask. The lender may consider an EMI holiday, tenure extension, revised EMI, or other restructuring option. Approval is not automatic, so share documents and ask for written terms.
What should I do if recovery agents harass me?
Stay calm, collect proof, ask for written communication, and complain to the lender’s grievance team. Recovery agents should not threaten, abuse, shame, or contact you at unreasonable hours.
Is loan settlement a good option?
Loan settlement can help when repayment is not realistic, but it may affect your credit report. Do not agree verbally. Get the settlement amount, deadline, and closure terms in writing before paying.
More guides on this topic: Can't Pay Your Buy Now Pay Later (BNPL) Dues? What Happens and What to Do · Drowning in Debt and Unable to Pay EMIs? A Calm, Step-by-Step Way Out · How Financial Counseling Can Reduce Your Debt Stress
Related help: see how our payday loan settlement service in India works, and know your rights if recovery agents harass you.
About Payday Rescue: Payday Rescue Pvt. Ltd. is a Bengaluru-based debt advisory and negotiation service that has helped 2K+ borrowers across India deal with payday, loan app, personal loan and credit card debt. We are not a lender, NBFC or law firm. Office: 1198, Basement Floor, 3rd Main, 8th Cross Rd, BDA Layout, Chandra Layout, Bengaluru 560026.
Talk to us: call or WhatsApp +91 98865 50910, email support@paydayrescue.in (Mon–Sat, 9am–9pm). About us · Contact · Free consultation
Last updated: October 2026.


Comments